

Barclays US
4.7

For me, the most useful banking app is not the one with the longest feature list; it is the one that helps me make a sound decision before a small purchase turns into a month-end surprise. That is the lens I would use when judging Barclays US: it is a free finance app from Barclays US, and its appeal is the idea of keeping everyday account checks and card management close at hand. I would treat it as a practical companion for people already using Barclays services, rather than a replacement for every financial tool they might need.
When a quick check is more useful than a full budget
The everyday value of a bank app often comes down to reducing the number of steps between a question and an answer. Before buying groceries, for example, I may want to check what is available, review recent activity, or confirm whether a payment has gone through. A focused banking app can make that routine less cumbersome than signing in through a browser or switching between several services. The benefit is modest but real: I can make a better-informed choice while I am already holding my phone.
That convenience works best when I use the app as a quick reference, not as a substitute for careful money management. A balance alone does not always tell the whole story: pending card activity, scheduled bills, and spending that has not yet appeared can affect what I can safely use. I would still leave room in my budget for upcoming commitments instead of treating the visible balance as permission to spend it all.
A calmer routine for card and account tasks
For a person who checks a Barclays account regularly, having routine tasks gathered in one place can cut down on friction. It is easier to build a habit of looking over recent activity when the route to it is familiar. I would make a brief check part of a weekly routine: scan transactions, note anything I do not recognize, and review the next few days of planned spending. That is more useful than opening the app repeatedly without a clear reason.
There is also a practical distinction between tracking and planning. An app can help me notice patterns, but I still need to decide what those patterns mean. If a category rises because of a one-off expense, I would not automatically treat it as a new monthly habit. If it keeps rising, I can use that observation to adjust a limit or change a routine. The tool is most helpful when it prompts a decision rather than simply displaying information.
A Seamless Banking Experience
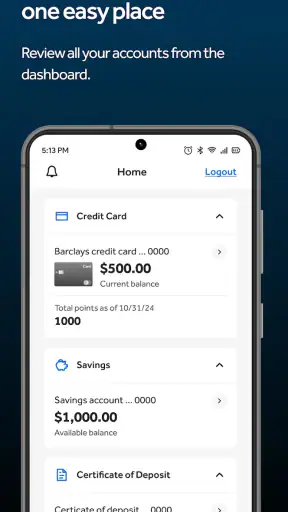
First off, let’s talk about the user interface. The Barclays US app nails it with its clean, intuitive design. No joke, it’s like they’ve read my mind and crafted an interface that’s easy to navigate, even for someone who tends to get lost in the digital wilderness. Everything you need is right there on the home screen, from checking your balance to paying your bills. It’s a one-stop shop for all your banking needs.
Simplicity at Its Best
One thing I love about this app is its simplicity. You know those apps that have a gazillion features crammed into them, and you end up using only half? Barclays US keeps it straightforward. You get what you need without the unnecessary fluff. Transferring money, viewing statements, and managing your cards can all be done with a few taps. And the cherry on top? It’s fast. No more staring at your screen waiting for pages to load. Hallelujah!
I would use that straightforward layout to separate quick errands from jobs that deserve more attention. A short balance check can happen while I am waiting in line, but reviewing a statement or handling a transfer is better done when I can concentrate and verify the details. That small habit matters: banking tasks are easy to rush on a small screen, and a clean interface does not remove the need to check amounts and recipients before confirming anything.
Compared with a general budgeting app, a bank’s own app has a different strength. It is the natural place to look at activity connected to that provider, while a separate budgeting tool may be more useful to someone trying to combine spending across several institutions or build a broader financial plan. I would not expect one app to do both jobs equally well. If Barclays is only one part of a complicated financial setup, keeping a separate overview may still make sense.
Security You Can Rely On
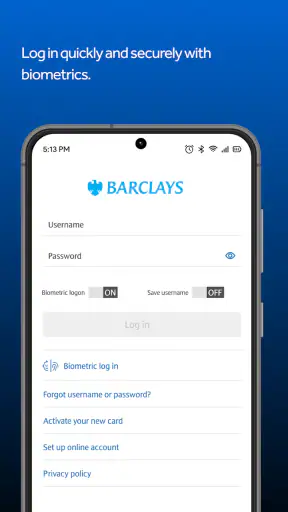
Now, let’s address the elephant in the room – security. We all want our financial data to be as secure as Fort Knox, right? Barclays US doesn’t skimp on security features. I felt pretty confident knowing they use advanced encryption and biometric login options, like fingerprint and facial recognition. It’s like having a digital bouncer for your bank account. Plus, they send you real-time alerts for transactions, keeping you in the loop 24/7.
Convenience and caution need to go together. I would enable alerts that help me notice account activity promptly, then take a moment to check whether a notification matches something I just did. Alerts are useful as an early signal, not a reason to assume that every transaction is correct or that every unusual message is genuine. I would open the app directly to review account activity rather than follow an unexpected message asking me to sign in.
Biometric access can make frequent checks less of a chore, but I would still keep my device’s own security in good shape and avoid leaving a banking session open where other people can use the phone. That is especially relevant if I share a device or lend it to family. The app’s security tools can support careful habits; they cannot replace them.
Features That Stand Out
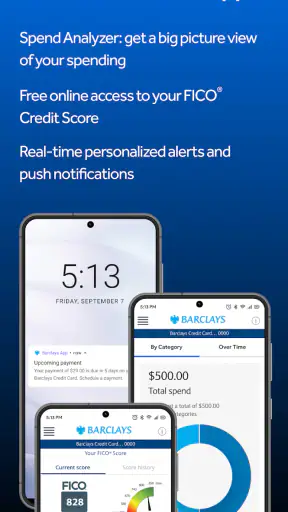
Alright, let’s dive into some of the standout features. The app offers a nifty spend tracking tool that breaks down your expenses into categories. It’s perfect for those of us who need a little help staying within budget. You can also set spending limits, and the app will give you a nudge if you’re close to hitting that mark. It’s like having a financial advisor in your pocket.
I would treat category tracking as a way to spot questions, not as a verdict on my spending. If a category looks unexpectedly high, I would compare the entries with receipts or statements before changing a budget. Categories can make patterns easier to see, but the useful step is deciding what to do next: pause optional purchases, move a planned expense, or simply recognize that a particular week is unusual.
One practical approach is to set a limit for a flexible area of spending, then check it before the point when I normally make purchases there. A limit is more actionable when I use it as a checkpoint, rather than waiting for a warning after most of the budget is gone. It can also be worth leaving a little breathing room for irregular costs. A strict target that ignores a necessary expense may create noise rather than help.
For a household, a small weekly review can turn the tracking view into a conversation about shared priorities. I would focus on broad patterns and upcoming costs, not scrutinize every individual purchase. That keeps the tool useful without making the app feel like a running scorecard. Someone who prefers a detailed, multi-account budget with custom planning may still want a dedicated budgeting service alongside their bank app.
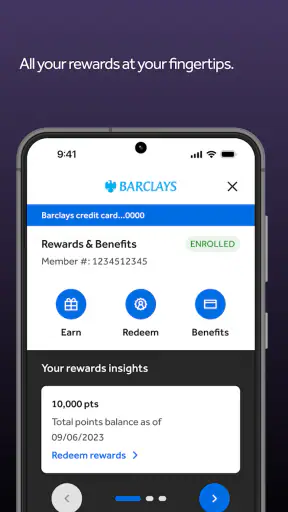
Another cool feature is the rewards section. If you’ve got a Barclays credit card, you can easily track your rewards and redeem them through the app. Whether it’s cash back, travel points, or shopping perks, it’s all laid out in a way that’s easy to understand and use.
I would check the rewards area before making a redemption decision, then compare the available options with what I actually value. A headline points balance is not the same thing as a useful benefit if I would not otherwise choose the offered reward. For someone who carries a Barclays credit card, bringing account activity and rewards into the same app can be convenient; a person without that card may get less from this part of the experience.
It is also worth treating rewards as a secondary benefit rather than a reason to spend more. I would not make an unnecessary purchase just to reach a threshold or earn points. The better test is whether the card already fits my normal spending and whether the redemption options suit my plans. That keeps rewards from distracting me from the more important job of managing payments responsibly.
Customer Service at Your Fingertips
Ever had a burning question at 2 AM? Barclays US has got you covered with their in-app customer service chat. I tried it out, and I was pleasantly surprised by the quick response time. It’s not every day you find customer support that’s both prompt and helpful. They’re available 24/7, so you can get assistance whenever you need it.
In-app support is especially handy when a question relates to something I am already viewing, because I can start from the banking context rather than explain the situation from scratch elsewhere. For a straightforward account query, that can be less disruptive than searching for a support route separately. For anything involving sensitive details, I would keep the conversation inside the app and be careful not to share security codes or passwords in response to unsolicited contact.
Chat is not automatically the best route for every problem. If an issue needs a careful explanation or involves several transactions, I would gather the relevant dates and details first so I can describe it clearly. If I need a formal record or a specific resolution, I would pay attention to the instructions support provides and keep track of the steps I have taken. The convenience of a chat window does not guarantee that every complex case will be resolved in one exchange.
Where it fits among finance apps
With an average rating of 4.7 from around 52,000 ratings, Barclays US has drawn a substantial audience; it has over a million installs and is rated for Everyone. Those figures suggest broad interest, but they do not tell me whether the app matches a particular person’s banking needs. I would judge it by whether I use Barclays services and whether its day-to-day account tools fit the way I handle money.
As a finance app, it sits between a mobile version of online banking and a dedicated money-management tool. The usual alternative is to use a browser for account access, which can be perfectly adequate but may feel less convenient for repeated checks. Another alternative is an independent budgeting app, which may suit someone who wants a consolidated picture across providers. I would choose the Barclays app for Barclays-related errands and keep the broader tool only if I genuinely need that wider view.
The app is free, and its current version is 8.6.0. It first appeared on February 16, 2012, and requires iOS 12 or later. Before installing, I would check that my device meets that requirement and that I am choosing the official Barclays US app, particularly if search results show similarly named services. A free download is useful, but the important decision is whether the app supports the accounts and tasks I actually use.
Who is likely to get the most from it
I would recommend trying it if you already bank with Barclays in the US and want a convenient place for regular account checks, card tasks, spending awareness, and rewards management where applicable. It is also a reasonable fit for someone who prefers a simple banking routine to a sprawling financial dashboard. The strongest case is everyday access: checking, reviewing, and taking care of familiar tasks without turning each one into a separate project.
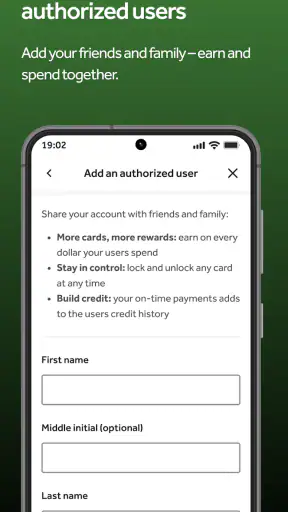
I would hesitate if you are looking for one app to combine accounts from many providers, produce a detailed household plan, or replace specialist investment and budgeting tools. Those are different jobs. I would also skip it if you do not use Barclays services, because a polished interface cannot make an unrelated bank app useful to you. For people who share finances, it is worth agreeing on how account access and spending reviews should work rather than assuming that installing the same app solves coordination.
A realistic routine might look like this: on payday, I check the account and note which bills are coming up; later in the week, I review recent card activity and compare flexible spending with my own limit; before a planned purchase, I check the balance while remembering that upcoming commitments still matter. If I notice something unfamiliar, I use the account view and support route to investigate instead of relying on a notification alone. That workflow turns quick access into a useful habit without asking the app to make financial decisions for me.
Final Thoughts
So, is the Barclays US app worth downloading? In my humble opinion, absolutely. Its user-friendly design, robust security features, and handy tools make it a strong contender in the world of banking apps. Whether you’re tech-savvy or someone who just wants to keep things simple, this app has something for everyone. Give it a try, and you might just find yourself wondering how you ever managed without it!
If you’re ready to streamline your banking experience, you can download the Barclays US app from the App Store or Google Play. Trust me, your future self will thank you.
4.7
6.71K Reviews
Pros
- User-friendly interface for easy navigation.
- Real-time transaction alerts enhance security.
- Customizable alerts for spending limits.
- Comprehensive financial tracking tools.
- Secure login with biometric authentication.
Cons
- Limited international transaction support.
- Occasional app crashes reported by users.
- Customer service can be slow to respond.
- No budgeting tool integration available.
- Requires frequent app updates.


